

There are two things nobody tells you before you land in the United States on an H-1B visa.
One: healthcare here is expensive in a way that doesn’t fully register until you see a bill. A single ER visit without insurance can run $3,000 to $10,000+. A broken arm. A bad kidney stone. A week in the hospital. These aren’t rare scenarios — they happen to people in their 30s who were completely healthy the month before.
Two: your H-1B status doesn’t come with any health coverage attached. USCIS doesn’t send you an insurance card. Your employer might — but “might” is doing a lot of work in that sentence.
This guide covers what you actually need to know: what your options are, what they cost in 2026, when you’re most at risk for a gap in coverage, and how to handle the tricky situations — job changes, layoffs, H-4 dependents, and the period right after you arrive.
Is Health Insurance Required for H-1B Visa Holders?
Not legally, no. The U.S. government doesn’t require H-1B holders to carry health insurance as a visa condition.
But “not required” and “optional” aren’t the same thing here. Medical debt is a leading driver of personal financial hardship in the United States — according to a 2019 study published in the American Journal of Public Health, medical bills contributed to approximately 66.5% of personal bankruptcies filed. The Kaiser Family Foundation (KFF) similarly documents that uninsured Americans face significantly higher out-of-pocket exposure than those with any form of coverage.
Without insurance, a single hospitalization can leave you owing more than your annual salary.
The practical requirement is this: once you’ve been in the U.S. long enough to be classified as a “resident alien” for tax purposes — typically 6 to 10 months after arrival — the Affordable Care Act (ACA) applies to you. At that point, if you don’t have ACA-compliant coverage, you could face tax penalties when filing your return.
(Source: healthcare.gov, KFF Health Insurance & Uninsured Resources)
When You First Arrive: Day 0 to Day 30
If you just landed and the insurance system already feels overwhelming, start here. Ignore everything else for now.
Step 1 — Ask your employer one question: “What date does my health insurance start?” Get the answer in writing. “Day one” and “after 90 days” are both common answers.
Step 2 — If there’s a gap, buy short-term coverage today. Don’t wait. Even a basic travel medical plan for $50–$150/month protects you from a $5,000+ ER bill while your employer plan activates.
Step 3 — Did your H-4 family arrive with you? They need their own coverage. Your employer plan may or may not include them. Check separately.
Step 4 — No SSN yet? You can enroll in some short-term plans with your passport and visa. For the ACA Marketplace, you’ll need an SSN or ITIN — SSN processing takes 2–4 weeks from your SSA office visit. Don’t let that delay stop you from buying gap coverage today.
That’s it for now. The rest of this guide fills in the details.
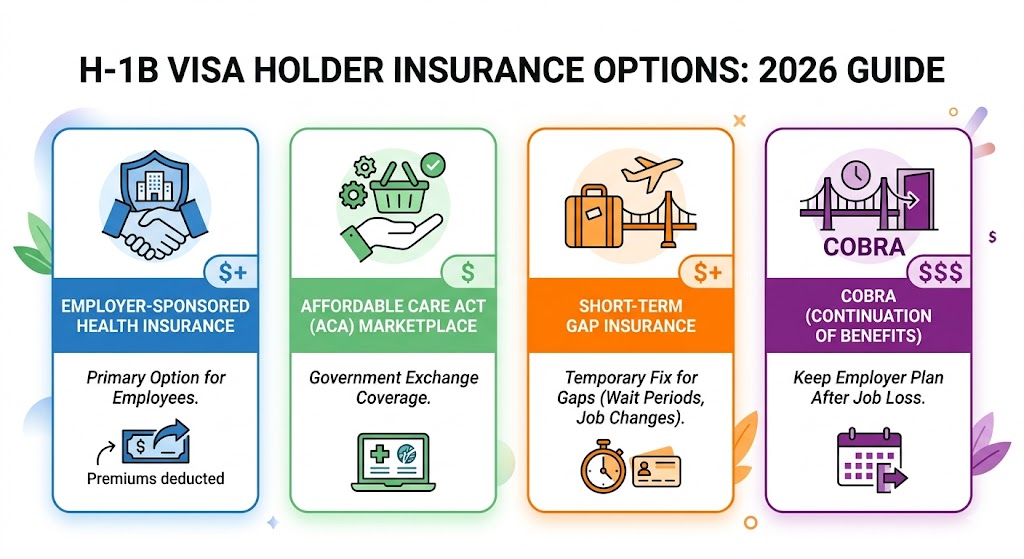
Your Four Real Options
1. Employer-Sponsored Health Insurance (Most Common)
Most large companies that sponsor H-1B workers offer group health insurance — plans through carriers like Aetna, Blue Cross Blue Shield, UnitedHealthcare, or Cigna. The employer pays part of the premium (sometimes 70–100% for the employee, less for dependents), and the rest comes out of your paycheck.
This is the best deal available to most H-1B holders. The coverage is ACA-compliant. The cost is usually lower than buying on your own. And enrollment happens through HR during your onboarding or the annual open enrollment period.
Things to check before you accept a job offer:
- Does coverage start on day one, or is there a 30–90 day waiting period?
- Are your H-4 dependents (spouse, children) covered, and at what cost?
- Which network is it — HMO, PPO, or HDHP with HSA? (Explained in the next section.)
- What’s the deductible and out-of-pocket maximum?
The waiting period question matters more than most people realize. If your employer’s plan starts 60 days after your hire date, you have 60 days without coverage. That’s the gap where people get hurt — sometimes literally.
Before accepting any offer, also make sure you understand the full cost structure of your H-1B — employer insurance premiums add up alongside petition fees, attorney costs, and other visa-related expenses.
2. ACA Health Insurance Marketplace
H-1B holders are “lawfully present” immigrants, which means you’re eligible to buy coverage through the federal or state marketplace at healthcare.gov. This is the route for people whose employers don’t offer insurance — common in consulting roles, staffing agency arrangements, and smaller companies.
What changed in 2026: The enhanced premium tax credits that made ACA plans affordable for millions of Americans expired on December 31, 2025. Congress didn’t extend them. In practical terms: someone earning $70,000/year who paid roughly $74/month for a Silver plan in 2025 is now looking at approximately $159/month in 2026 — or more, depending on the state and plan. The “subsidy cliff” also returned. If your household income exceeds 400% of the federal poverty level (about $62,600 for a single person), you get no premium tax credits at all.
(Source: 1099healthins.com — commercial comparison platform)
State-level note: If you live in California, New York, Massachusetts, or Washington, these states run their own subsidy programs that continue even after the federal enhanced credits expired. Don’t use healthcare.gov — check your state’s exchange directly: Covered California (coveredca.gov), NY State of Health (nystateofhealth.ny.gov), Massachusetts Health Connector (mahealthconnector.org), or Washington Healthplanfinder (wahealthplanfinder.org). The savings difference can be significant.
SSN / ITIN note: To enroll in the Marketplace, you need either a Social Security Number (SSN) or an Individual Taxpayer Identification Number (ITIN). If you just arrived and haven’t received your SSN yet, visit your local Social Security Administration (SSA) office first — SSN processing typically takes 2–4 weeks. In the meantime, a short-term travel medical plan can cover the gap until you’re able to enroll.
Special Enrollment Periods (SEPs): You can only join the Marketplace during annual open enrollment (November 1 – January 15) or when you have a qualifying life event: losing employer coverage, moving to a new state, having a baby, getting married. Losing a job counts. Starting a new job and losing your old coverage also counts.
3. Short-Term / Travel Medical Insurance (Gap Coverage)
Short-term and travel medical insurance plans are not ACA-compliant. They don’t cover pre-existing conditions, maternity, mental health, or preventive care. They are not a substitute for a real health plan.
But they are good at one thing: keeping you from a catastrophic out-of-pocket situation during a coverage gap of a few weeks or months.
When this matters:
- You just arrived and your employer’s plan doesn’t start for 30–60 days
- You changed jobs and there’s a gap between your old and new coverage
- You were laid off and you’re in the 60-day COBRA election window
- Your H-4 dependent just arrived and isn’t yet enrolled in any plan
Carriers like SafetyWing, GeoBlue, Cigna Global, and Seven Corners offer plans designed for international workers. Insubuy.com is a common comparison platform in the H-1B community (commercial comparison platform).
Cost: typically $50–$200/month depending on your age, deductible, and coverage limits.
One real scenario: an H-1B software engineer arrived without coverage and needed urgent care for flu symptoms before their employer plan activated. They had purchased temporary H-1B medical insurance — a bill of $380 was reduced to a small copay. Without that coverage, they’d have paid full price out of pocket. (Source: americanvisitorinsurance.com)
4. COBRA
If you leave a job and were covered under an employer group plan, you have the right to continue that exact coverage for up to 18 months under COBRA (Consolidated Omnibus Budget Reconciliation Act).
The catch: you pay the full premium — what you paid plus what your employer paid — plus a 2% administrative fee. That typically runs $600–$900/month for an individual, more for families.
COBRA is worth considering when:
- You’re between jobs and don’t want to risk a gap in coverage
- You’re mid-treatment and don’t want to change networks
- You have dependents and the Marketplace alternative would cost just as much
You have 60 days to elect COBRA after losing coverage. You can wait and decide retroactively — if you have a medical event during that 60-day window, you can elect COBRA after the fact and it’ll cover that event. Just pay the back premiums.
Understanding Plan Types: HMO vs. PPO vs. HDHP
If you’re from India or another country with a national healthcare system, these acronyms probably mean nothing to you yet. Understanding them before you pick a plan saves real money.
HMO (Health Maintenance Organization): You pick a primary care physician (PCP) who coordinates all your care. Lower monthly premiums, lower out-of-pocket costs, but you must stay in-network. Going out of network is generally not covered.
PPO (Preferred Provider Organization): More flexibility — you can see any doctor in or out of network without a referral, though in-network costs are lower. Higher monthly premiums than HMOs.
HDHP (High Deductible Health Plan) with HSA: Lower monthly premiums, but you pay more out of pocket before coverage kicks in (the deductible is higher). Paired with a Health Savings Account (HSA), which lets you set aside pre-tax money for medical expenses. Good if you’re healthy and want to build tax-advantaged savings; riskier if you have chronic conditions or expect regular medical visits.
For most H-1B holders arriving in the U.S. for the first time, a PPO or employer HMO is the safest default. The network flexibility of a PPO matters when you don’t yet know which doctors or hospitals are near you and haven’t established care with anyone.
The Coverage Gap Problem — And Why It Catches People Off Guard
Here’s the situation that shows up constantly in H-1B forums and Reddit threads.
Someone switches jobs. Their old employer’s coverage ends on the last day of employment. Their new employer’s plan doesn’t start until 60 or 90 days in. That’s a gap. During that gap, they’re uninsured.
From discussions aggregated by Stilt.com — an H-1B community resource platform — one person described their insurance plan being deactivated after a miscommunication, leaving them uninsured for three months with no re-enrollment available until October. No coverage through a medical checkup, a family ER visit, nothing.
Another warning from the same thread: “An accident or health emergency paying out-of-pocket without insurance could potentially bankrupt you on an H-1B visa before you qualify for any subsidized care.”
That’s not catastrophizing. That’s accurate.
The fix requires planning: know your coverage end date, know your new coverage start date, and buy a short-term plan to fill the gap. Don’t wait to see if you’ll need it.
If you’re navigating an H-1B extension at the same time as a job transition, the 240-day rule affects your right to keep working — and your insurance situation is running on the same clock. Understanding how the 240-day rule and grace period interact during a job change or extension will help you avoid two crises at once.
H-4 Dependents: The Coverage That’s Hardest to Figure Out
If your spouse and children are in the U.S. on H-4 visas, their insurance situation is separate from yours — and often messier.
Some employers include H-4 dependents in their group plans. Many don’t, or charge significantly more to add family members. And unlike you, your spouse on H-4 may not have independent access to employer-sponsored insurance if they’re not working. If your spouse has an H-4 EAD work authorization and is employed — which allows H-4 holders to work legally in the U.S. — their employer may offer coverage directly.
Options for H-4 dependents:
- Employer group plan (add as dependent — check the cost, it varies widely)
- ACA Marketplace (H-4 holders are lawfully present and eligible to enroll)
- Short-term / travel medical for gaps upon arrival
When your spouse first arrives in the U.S. on H-4, there’s often a gap between their arrival and when they can be enrolled in any plan. A temporary travel medical policy for 30–60 days is standard practice in the H-1B community.
What About Medicaid and Medicare?
Medicare: Not available to H-1B holders. Medicare requires U.S. citizenship or lawful permanent resident status for at least five continuous years. Your H-1B doesn’t qualify, regardless of how long you’ve been here.
Medicaid: Full Medicaid is generally not available to H-1B holders. Some states provide emergency Medicaid — coverage for life-threatening emergencies only. Don’t count on Medicaid as a primary health plan.
(Source: loigica.com)
If You Get Laid Off
Layoffs hit H-1B workers particularly hard because everything — immigration status, health coverage — is tied to the employer.
Immediate steps on the insurance side:
- Elect COBRA if you need to maintain coverage and can afford it. You have 60 days. Costs are high but it’s continuous coverage on the same plan with the same network.
- Apply for a Marketplace Special Enrollment Period. Losing employer coverage is a qualifying event — you have 60 days to enroll.
- Buy a short-term plan if you just need a stopgap while you figure out your next move.
On the immigration side — the 60-day H-1B grace period starts the moment employment ends. If your employer cancels your visa outright, different rules apply. The H-1B visa revocation guide covers what happens to your grace period, your status, and your options if your employer cancels your visa — including the exact steps USCIS expects you to take.
The health insurance clock and the immigration clock run simultaneously. That’s why planning both at the same time matters.

H-1B & Immigrant Health Guide
2026 Health Insurance Cost Snapshot
Ballpark figures — actual costs vary by state, age, plan tier & carrier
Employer-Sponsored
Monthly Cost
$0 – $300 / mo
Best For
Most H-1B workers — always the first choice when available
ACA Marketplace
(No Subsidy)
Monthly Cost
$350 – $600 / mo
Best For
Self-employed or those without an employer plan
ACA Marketplace
(With Subsidy)
Monthly Cost
$50 – $200 / mo
Best For
Income below ~$62,600/year — significant savings available
COBRA
Monthly Cost
$600 – $900 / mo
Best For
Job loss, mid-treatment continuity, or covering dependents
Short-term / Travel Medical
Monthly Cost
$50 – $200 / mo
Best For
Gap coverage only — not a substitute for primary insurance
* All figures are estimates for 2026. Consult a licensed health insurance broker for personalized advice.
Note: ACA subsidies got significantly less favorable in 2026 after the enhanced credits expired. High earners on H-1B (above ~$62,600 for a single person) qualify for no federal subsidies at all — unless you’re in a state with its own subsidy program (see the ACA section above).
Health insurance costs directly affect your overall financial picture in the U.S. — something worth factoring into salary negotiations, particularly when reviewing whether your employer is covering costs fairly. The H-1B sponsorship guide covers how to navigate the employer salary conversation, including what compensation components to negotiate beyond base pay.

FAQs — Real Questions From H-1B Holders
Yes. H-1B holders are “lawfully present” immigrants and are eligible to purchase Marketplace plans. You can also qualify for premium tax credits based on income. However, as of 2026, the enhanced subsidies have expired for most people. Check your state’s exchange first — California, New York, Massachusetts, and Washington have their own subsidy programs that may still apply to you.
Buy a short-term or travel medical insurance plan for those 60 days. It’s not ACA-compliant and won’t cover everything, but it covers accidents, sudden illness, and ER visits — the things that could cost you tens of thousands without any coverage. Plans from GeoBlue, SafetyWing, or via Insubuy (commercial comparison platform) run roughly $50–$150/month.
No. USCIS doesn’t require health insurance as a visa condition. That said, once you qualify as a resident alien for tax purposes, ACA rules apply. And practically speaking, going uninsured in the U.S. is a financial gamble that has bankrupted people far more financially stable than the average H-1B worker.
Yes. H-4 holders are lawfully present and can enroll in ACA Marketplace plans. They can also be added to your employer group plan as a dependent — check if your employer offers this and what the additional premium cost is. If your spouse is authorized to work via H-4 EAD, their employer may also offer coverage directly. The H-4 EAD guide explains the full eligibility process for work authorization and what it takes to apply.
Your employer-sponsored coverage ends when your employment ends. You can elect COBRA for up to 18 months or apply for a Marketplace Special Enrollment Period. The H-1B visa revocation guide covers what happens to your status, your grace period, and your legal options when an employer cancels your petition.
Yes. If your employer offers an HSA-eligible HDHP, you can contribute to and use an HSA. The tax benefit works the same way as for citizens. One thing to note: if you eventually leave the U.S., you can continue using the HSA for qualified medical expenses, but contributions must stop once you’re no longer covered by an HDHP.
Your insurance plan has contracts with specific doctors and hospitals (the “network”). When you use in-network providers, you pay lower rates because the insurer has pre-negotiated them. Out-of-network care costs significantly more — sometimes not covered at all under HMO plans. This matters especially when you first arrive: don’t just go to the nearest urgent care. Check whether it’s in your network first.
Having private health insurance — employer or Marketplace — shows you’re not relying on government assistance, which is what the Public Charge rule looks at. Using Medicaid, on the other hand, can be a factor in a Public Charge assessment. The H-1B to green card timeline guide covers what actually affects your green card case at each stage.

What to Do Before Your First Day at Work
In the two weeks before you start a new H-1B job:
- Call HR and ask exactly when your health insurance starts. Get it in writing.
- If there’s a gap, price short-term coverage immediately. Don’t wait until after you’ve started.
- Check whether your H-4 dependents are covered. If yes, get the enrollment form ready. If no, they need separate coverage.
- Look at the plan options carefully. Your employer may offer multiple tiers — understand the deductible and out-of-pocket maximum before picking the cheapest premium.
- If you’re transitioning from OPT, confirm your F-1 coverage end date. The period between OPT ending and H-1B activating is a common time for coverage lapses. The OPT-to-H-1B transition guide walks through the full visa status change and what to do on each side of that gap.
Getting your health coverage sorted also connects to your broader financial setup in the U.S. — including your tax filing situation. The best tax software for H-1B holders covers how to report health coverage correctly on your return, including the difference between Form 1040-NR and resident alien filing status.
Bottom Line
Health insurance in the U.S. is confusing, expensive, and more important than most H-1B holders realize until something goes wrong. The system doesn’t have a safety net designed for you — Medicare and Medicaid are mostly off the table, and the ACA subsidies that made the Marketplace a decent backup got significantly worse in 2026 for most earners.
Your best options, in rough order of preference:
- Employer plan starting day one — no gap
- Employer plan with short-term gap coverage for any waiting period
- ACA Marketplace if your employer doesn’t offer coverage and your income qualifies for subsidies
- COBRA as a bridge after job loss, while you sort out your next move
- Short-term travel medical as a fallback for brief gaps only
Understanding the H-1B eligibility requirements and keeping up with rule changes in 2026 helps you stay ahead of situations where coverage might slip through the cracks.
Health coverage isn’t glamorous. But it’s the thing that separates a minor inconvenience from a financial emergency. Get it figured out before you need it.
Disclaimer: This article is for informational purposes only and does not constitute legal, financial, or insurance advice. Health insurance rules, ACA subsidies, and immigration regulations change frequently. Always verify current information with a licensed insurance broker, immigration attorney, or official government sources such as healthcare.gov and uscis.gov before making any decisions.