

Key Takeaways
- There are TWO separate 5-year rules: one for earnings (starts with your first-ever Roth contribution) and one for each conversion you make
- Your contributions are always accessible tax-free and penalty-free at any age—no waiting period
- The clock starts January 1 of the tax year, not your deposit date (contribute in December to gain almost a full year)
- Each conversion gets its own 5-year countdown if you’re under 59½—withdraw too early and you pay a 10% penalty
- Roth 401(k) and Roth IRA have separate clocks that don’t count toward each other
A 42-year-old needed emergency cash from her Roth IRA. She’d been contributing for 15 years, so she figured withdrawing money would be penalty-free. Her brokerage couldn’t tell her how much she’d contributed versus how much were earnings—she’d switched firms twice and nobody kept the full history.
After three weeks of requesting IRS transcripts and digging through old emails, she finally pieced it together.
This happens constantly. The Roth IRA 5-year rule sounds simple until you actually need your money. Then you discover there’s not one rule—there are several, and mixing them up costs thousands in unexpected taxes and penalties.
The Two Different 5-Year Rules (And Why Each Matters)
Rule 1: The Earnings Rule (Your Lifetime Roth Clock)
To withdraw earnings tax-free and penalty-free, you need both:
- Your first Roth IRA opened for at least 5 tax years
- You’re 59½+ (or have an exception: disability, death, or $10K for first-time home)

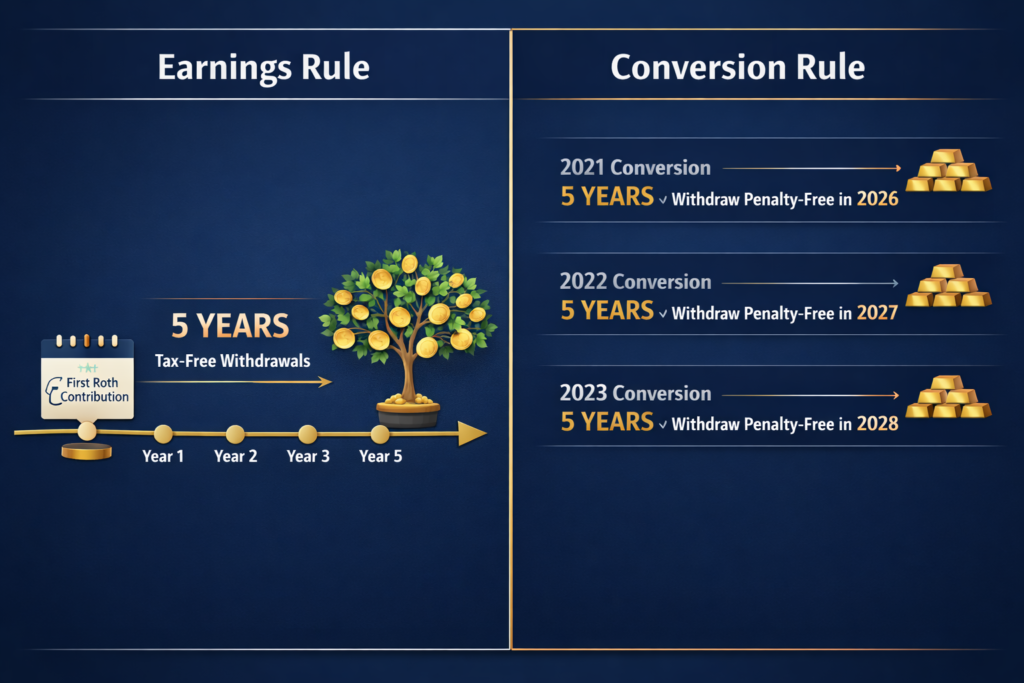
The critical detail: This clock starts January 1 of the tax year you made your first contribution to ANY Roth IRA, ever. It’s a one-time, lifetime clock.
Example: Open your first Roth in 2020 at age 25 with $1,000. Open a second Roth in 2024 at a different brokerage with $50,000. Both accounts share the same 5-year clock starting January 1, 2020.
Rule 2: The Conversion Rule (Each Gets Its Own Clock)
Every single Roth conversion starts its own separate 5-year countdown.
If you’re under 59½: Withdraw a conversion before its 5-year period ends = 10% penalty on that amount If you’re 59½+: The conversion penalty disappears entirely—access conversions anytime
Example of multiple conversions:
- 2021: Convert $15,000 (accessible January 2026 if under 59½)
- 2023: Convert $15,000 (accessible January 2028 if under 59½)
- 2024: Convert $15,000 (accessible January 2029 if under 59½)
Scenario: It’s 2027, you’re 56, and you withdraw $20,000. The first $15,000 comes from your 2021 conversion (no penalty—6+ years old). The next $5,000 comes from your 2023 conversion (10% penalty = $500 because it’s only 4 years old).
What You Can Withdraw Right Now: The IRS Ordering Rules
The IRS forces withdrawals in this exact order:
| Type | Tax? | Penalty if Under 59½? | Waiting Period? |
|---|---|---|---|
| Contributions | Never | Never | None — anytime access |
| Conversions (oldest first) | No | Yes, if less than 5 years old | 5 years per conversion |
| Earnings | Yes, if 5-year rule not met | Yes, unless exception applies | Until age 59½ + 5 years |
Real example showing why this matters:
Your Roth IRA balance: $85,000
- Direct contributions: $45,000
- 2020 conversion: $20,000
- 2023 conversion: $10,000
- Earnings: $10,000
- Your age: 57

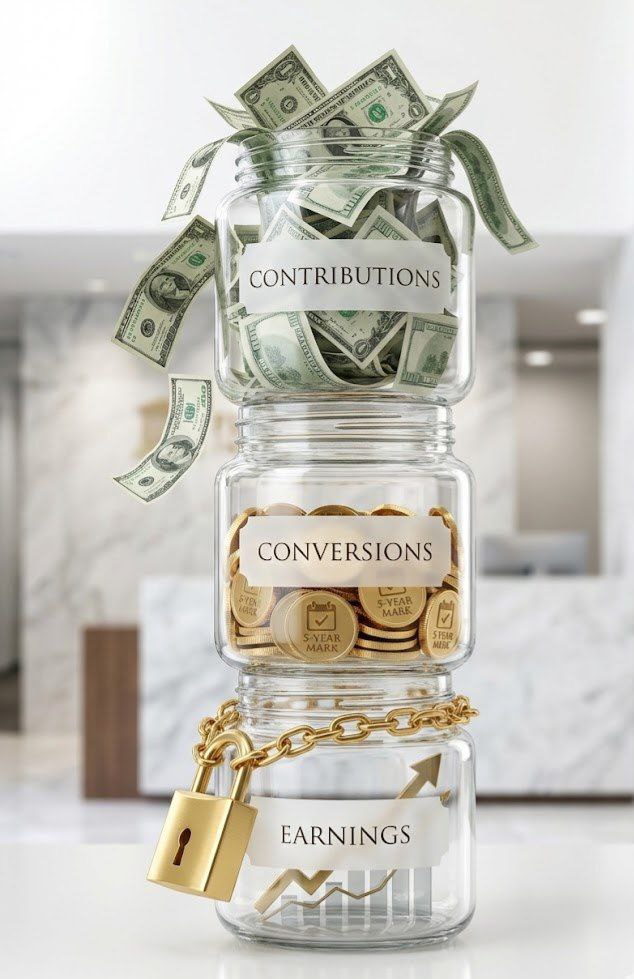
You withdraw $50,000:
- First $45,000 = contributions (no tax, no penalty)
- Next $5,000 = from 2020 conversion (no tax, no penalty—7+ years old)
- Total cost: $0
If you withdrew $70,000 instead:
- First $45,000 = contributions (free)
- Next $20,000 = 2020 conversion (free—cleared 5 years)
- Next $5,000 = 2023 conversion (10% penalty = $500 because only 4 years old)
Roth 401(k) vs Roth IRA: Critical Differences
The clocks are completely separate. Having a Roth 401(k) for 10 years doesn’t satisfy a new Roth IRA’s 5-year rule.
When you roll Roth 401(k) to Roth IRA:
- Contributions from the 401(k) become immediately accessible
- Earnings follow the Roth IRA’s 5-year timeline, not the 401(k)’s age
Example: Roll $120,000 from Roth 401(k) to Roth IRA ($90,000 contributions, $30,000 earnings). You can immediately withdraw $90,000. The $30,000 in earnings waits until you’re 59½ and your Roth IRA meets the 5-year earnings rule.
The January 1 Backdating Strategy
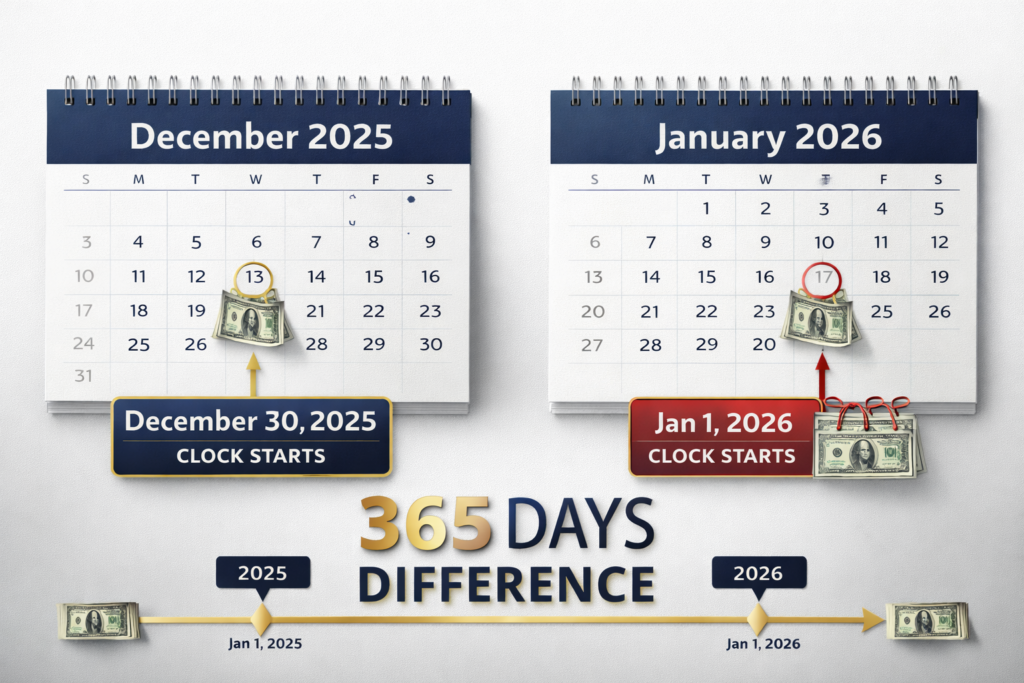
The 5-year clock starts January 1 of the tax year, not your deposit date.
- Contribute December 30, 2025 → Clock starts January 1, 2025
- Contribute January 2, 2026 → Clock starts January 1, 2026
- Difference: One full year from contributing 3 days earlier
The $1 strategy: A 28-year-old couldn’t afford serious contributions yet, but opened a Roth with $1 in late December 2020. When he started contributing heavily in 2024, his account was already 4+ years old. His 5-year earnings rule was satisfied at age 33 instead of 37.
Backdoor Roth IRA: How It Works
High earners who exceed Roth IRA income limits ($168,000 single / $252,000 married for 2026) use this legal workaround.
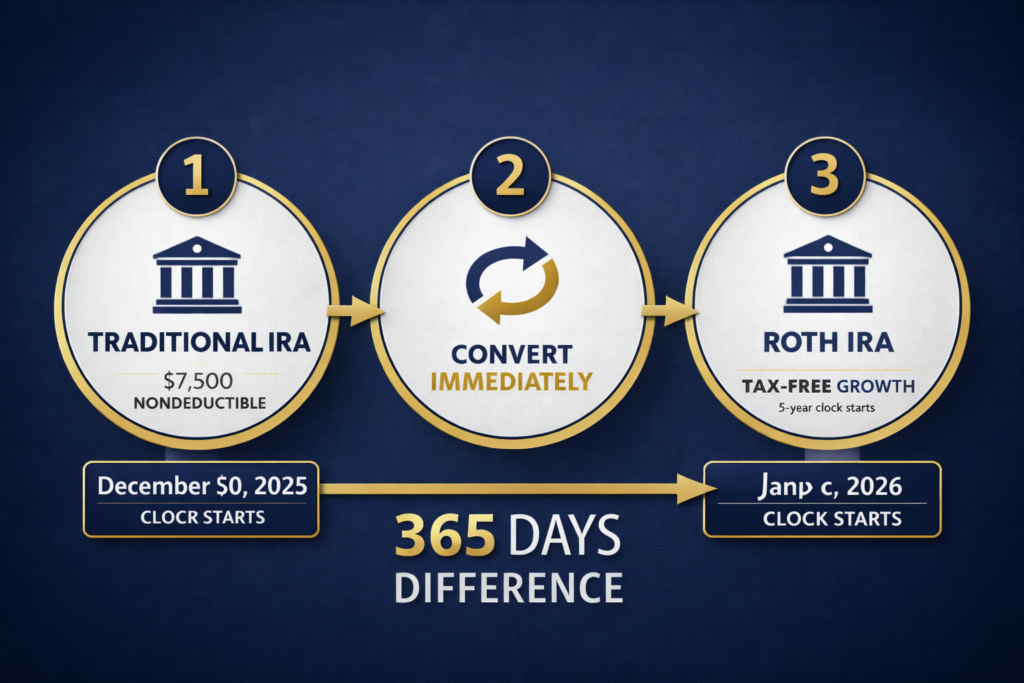
3-step process:
- Contribute to a traditional IRA (nondeductible): $7,500 if under 50, $8,600 if 50+
- Convert that traditional IRA to Roth immediately
- Pay tax only on growth (usually $0-20 if done quickly)
Result: The converted amount enters your Roth with its own 5-year clock starting January 1 of the conversion year.
The Pro-Rata Rule Trap
If you have ANY pre-tax money in traditional IRAs, conversions get messy and expensive.
Example:
- Traditional IRA #1: $95,000 (pre-tax)
- Traditional IRA #2: $5,000 (fresh nondeductible contribution)
You convert the $5,000 thinking it’s tax-free. Wrong. The IRS calculates:
- Total IRA balance: $100,000
- After-tax portion: 5%
- Pre-tax portion: 95%
When you convert $5,000: Only $250 is tax-free. You owe tax on $4,750.
Solution: Roll pre-tax IRA money into a current employer’s 401(k) before doing backdoor Roth.
Common Mistakes That Cost Money
Mistake 1: “My brokerage tracks everything” An investor switched brokerages twice over 20 years. His current firm only showed the transferred balance—not his $85,000 contribution history. He eventually got records from IRS transcripts (Form 5498), but it took weeks during an emergency.
Lesson: Keep your own spreadsheet. Track every contribution and conversion.
Mistake 2: “I converted $50K last year, so I can withdraw it now” A 54-year-old converted $50,000 in 2025 and withdrew it in 2026. Cost: $5,000 penalty (10% of $50K) because conversions have 5-year clocks if you’re under 59½.
Mistake 3: “The customer service rep said…” A 60-year-old was told he needed to wait 5 years before touching a “new” Roth IRA. Wrong. He’d opened his first Roth at age 40—the earnings rule was satisfied 20 years ago. Not every rep understands these rules. Verify with IRS Publication 590-B.
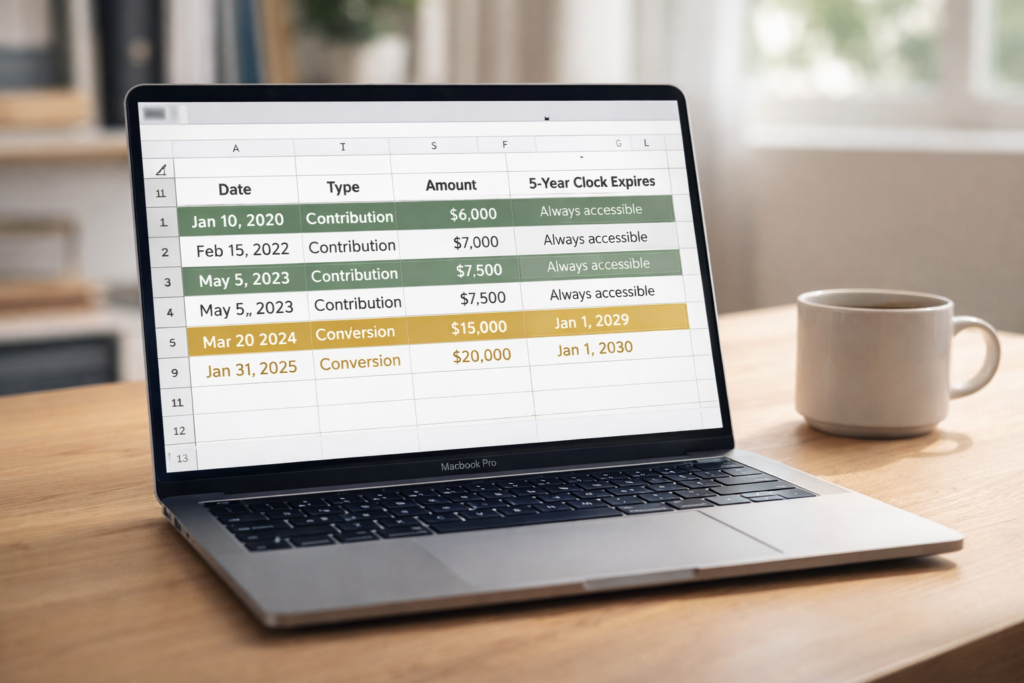
Mistake 4: “I’ll track my conversions later” A 56-year-old did annual $20K conversions for 6 years but kept no records. At age 58, she couldn’t prove which conversions cleared their 5-year clocks. To be safe, she left potentially accessible money locked up.
Spreadsheet solution:
| Date | Type | Amount | 5-Year Clock Expires |
|---|---|---|---|
| Jan 10, 2022 | Conversion | $15,000 | Jan 1, 2027 |
| Feb 15, 2023 | Backdoor Roth | $6,500 | Jan 1, 2028 |
| Mar 20, 2024 | Conversion | $20,000 | Jan 1, 2029 |
When Should You Convert to a Roth?
Conversions make sense when: You’re in a low-income year (retired early, between jobs, business loss) You want to avoid Required Minimum Distributions (start at age 73) You can pay conversion taxes from non-retirement funds You’re age 60-72 (retired but before RMDs begin)
Skip conversions when: You’re currently in a high tax bracket (32-37%) You’ll need the money within 5 years and you’re under 59½ The conversion triggers Medicare IRMAA surcharges You’d have to pay taxes from the IRA itself
Smart strategy: Convert enough to fill your current tax bracket without jumping to the next one.
Example: You’re married, retired, with $60K income. The 12% bracket ends at $96,950. Room left: $36,950. Convert exactly that amount and pay only 12% tax.
Exceptions to the 10% Penalty
Even if you don’t meet the 5-year rule or aren’t 59½, these exceptions waive the 10% penalty:
- First-time home purchase: Up to $10,000 lifetime
- Qualified education expenses: For you, spouse, children, grandchildren
- Medical expenses: Amount exceeding 7.5% of AGI
- Disability: Permanent and total
- Death: Distributions to beneficiaries
- Substantially equal payments (72t): Must continue for 5 years or until 59½
Important: These waive the penalty but don’t automatically make earnings tax-free. You still need the 5-year earnings rule for completely tax-free withdrawals.
Your Action Checklist: Protect Yourself
Open a Roth IRA before December 31 with even $1 to start your 5-year clock Track contributions in a spreadsheet: year and amount Track conversions with dates—each has its own 5-year clock Save Forms 5498 and 8606 every year (contribution and conversion proof) Download IRS tax transcripts every 3 years as backup Create a withdrawal plan before taking money out—know what’s accessible

Take Action This Week
The Roth IRA 5-year rules are complex, but you don’t need perfection—just basic tracking and planning.
If you don’t have a Roth IRA: Open one before December 31 with $1. You’ll start your lifetime earnings clock immediately.
If you have one: Spend 15 minutes creating a tracking spreadsheet. List every contribution and conversion with dates.
If you’re doing conversions: Track each one separately. Know when each 5-year clock expires.
If you might need money: Calculate what’s accessible right now—all contributions plus conversions that cleared 5 years.
The mistakes happen when people don’t track their money or assume all Roth dollars are the same. They’re not. Contributions, conversions, and earnings follow completely different rules.
Start tracking today. Your future self—the one who needs emergency funds, wants to buy a house, or retires early—will thank you for taking this seriously.
Don’t let the 5-year rule scare you. It’s just something you plan around, not something that blindsides you when you need your money.
Frequently Asked Questions
Not for contributions—those are yours anytime, any age. The 5-year rule only affects earnings and conversions.
If you’re also 59½+, everything becomes tax-free and penalty-free. If younger, conversions become accessible but earnings still wait until 59½.
Yes, it remains legal for 2026. Watch the pro-rata rule if you have pre-tax IRA money.
No. Conversions only happen in the year they occur—you can’t backdate them. Regular contributions can be made until Tax Day for the previous year.
No. They’re completely separate accounts with separate clocks.
Research Sources & Deep Research URLs
Primary Government Sources:
- IRS Publication 590-B (2024): Distributions from Individual Retirement Arrangements
- URL:
https://www.irs.gov/publications/p590b - Used for: Official 5-year rule definitions, ordering rules, exceptions
- URL:
- IRS Topic No. 309: Roth IRA Contributions
- URL:
https://www.irs.gov/taxtopics/tc309 - Used for: Contribution limits, income thresholds
- URL:
- IRS Form 8606 Instructions
- URL:
https://www.irs.gov/forms-pubs/about-form-8606 - Used for: Nondeductible IRA basis, conversion documentation
- URL:
Major Financial Institution Resources:
- Fidelity – Roth IRA Withdrawal Rules
- URL:
https://www.fidelity.com/building-savings/learn-about-iras/roth-ira-withdrawal - Used for: Real-world examples, ordering rules clarification
- URL:
- Vanguard – Roth IRA Distribution Rules
- URL:
https://investor.vanguard.com/investor-resources-education/iras/roth-ira-distribution-rules - Used for: Conversion rules, qualified distributions
- URL:
- Charles Schwab – Understanding Roth IRA Distribution Rules
- URL:
https://www.schwab.com/ira/roth-ira/withdrawal-rules - Used for: Earnings vs. contributions, penalty exceptions
- URL:
Financial Planning & Tax Professional Sources:
- Kitces.com – The Two Five-Year Rules For Roth IRA Contributions And Conversions
- URL:
https://www.kitces.com/blog/understanding-the-two-5-year-rules-for-roth-ira-contributions-and-conversions/ - Used for: Technical nuances, professional advisor perspective
- URL:
- The White Coat Investor – Backdoor Roth IRA Tutorial
- URL:
https://www.whitecoatinvestor.com/backdoor-roth-ira-tutorial/ - Used for: Backdoor Roth process, pro-rata rule examples
- URL:
- Bogleheads Wiki – Roth IRA
- URL:
https://www.bogleheads.org/wiki/Roth_IRA - Used for: Community insights, common mistakes
- URL:
Reddit Community Research (Anonymized Real Stories):
- r/personalfinance – Roth IRA discussions
- URL:
https://www.reddit.com/r/personalfinance/search/?q=roth%205%20year%20rule - Used for: Real user experiences, common confusion points
- URL:
- r/financialindependence – Early retirement Roth strategies
- URL:
https://www.reddit.com/r/financialindependence/ - Used for: Roth conversion ladders, early withdrawal strategies
- URL:
News & Updates:
- Forbes – Roth IRA Rules
- URL:
https://www.forbes.com/advisor/retirement/roth-ira-rules/ - Used for: 2026 limits, current regulations
- URL:
- Investopedia – Roth IRA 5-Year Rule
- URL:
https://www.investopedia.com/roth-ira-5-year-rule-4769803 - Used for: Definitions, terminology
- URL:
Legal & Regulatory:
- 26 U.S. Code § 408A – Roth IRAs
- URL:
https://www.law.cornell.edu/uscode/text/26/408A - Used for: Legal foundation of Roth IRA rules
- URL:
- SECURE Act 2.0 Provisions
- URL:
https://www.congress.gov/bill/117th-congress/house-bill/2954 - Used for: Updated RMD ages, inherited IRA rules
- URL:
Disclaimer:
The information provided in this article is for educational purposes only and should not be considered as financial advice. Always consult with a financial advisor or credit counselor before making any significant decisions regarding debt repayment or financial strategies. The strategies discussed may not be suitable for everyone and results may vary depending on individual circumstances.