

If you’re trying to decide between the debt snowball and debt avalanche methods, you’ve probably noticed something frustrating. One source says “always pay the highest interest first.” Another says “small wins matter more than math.” Then Reddit, calculators, and banks all tell you something slightly different.
So you’re left wondering: Am I about to make the wrong move and waste years?
That confusion is normal. Most advice skips over real-life details — cash flow stress, missed payments, changing interest rates, and the emotional toll of carrying debt month after month. Let’s slow this down and talk about what actually matters for you, not in theory.
Why Most People Don’t Stick to Any Payoff Method
The biggest problem isn’t choosing snowball or avalanche.
It’s that many people pick a method that looks good on paper but doesn’t survive real life.
Common reasons plans fail:
Your income isn’t stable every month
An emergency forces you back onto the card
You get mentally exhausted tracking too many balances
Neither method accounts for these issues by default. They assume steady income, no emergencies, and perfect follow-through — which isn’t how real people live.
I’ve seen people read ten articles, open three spreadsheets, and still freeze because every option feels risky. The debate around the debt snowball vs avalanche method often turns into overthinking, not action. At that point, the question isn’t really which debt payoff method is better — it’s which one you’ll actually follow when life gets messy.
Understanding where snowball and avalanche break down is more important than understanding how they work.

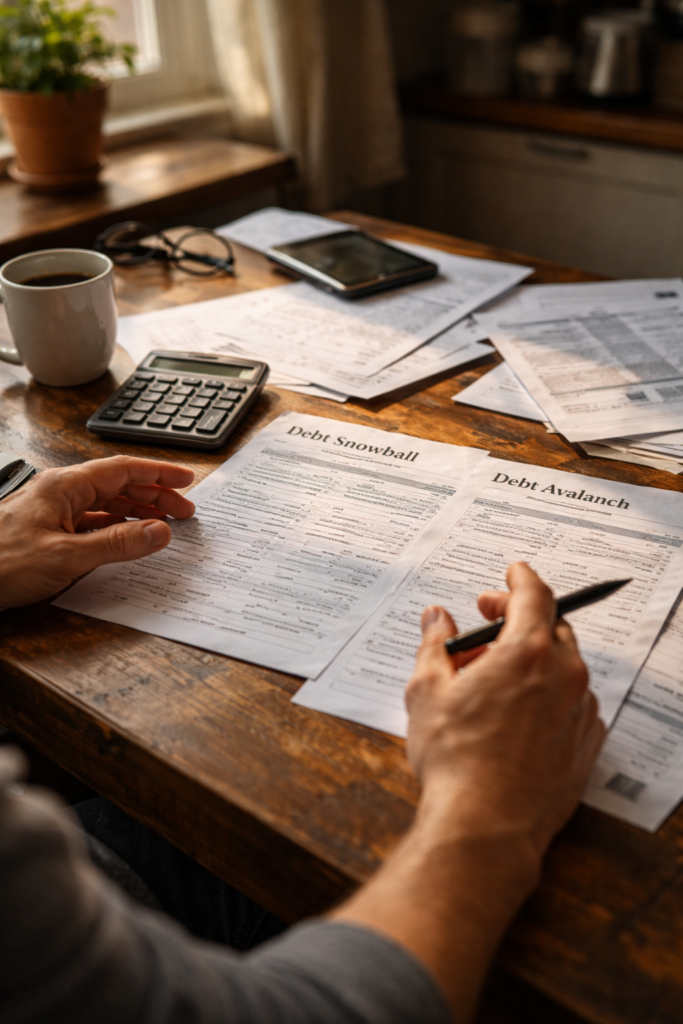
The Debt Avalanche: Where Math Makes Sense — and Where It Breaks
The avalanche method tells you to focus on the highest interest rate first. Mathematically, it reduces total interest paid. That part is true.
Where it works well:
You have predictable income
You can comfortably pay more than the minimum every month
The highest-interest debt is not massive compared to your income
Where it backfires:
The highest-interest balance is large and takes years to move
You see little visible progress early on
Motivation drops and you start skipping extra payments
You underestimate how stressful long timelines feel
For many people, the math advantage disappears the moment consistency breaks.
I’ve watched people start strong with avalanche, convinced they’d power through it. A few months in, the balance barely moved and the excitement faded. Eventually, they paid off a smaller card first to feel some progress, then returned to the high-interest debt with renewed energy. That switch didn’t mean failure — it’s what kept them moving forward.
The Debt Snowball: Emotional Relief with Hidden Costs
The snowball method focuses on small balances first, regardless of interest rate. You close accounts faster and feel progress sooner.
Where it helps:
You feel overwhelmed by multiple payments
Cash flow is tight and reducing minimums matters
You’re close to quitting unless you see progress
Where it hurts:
High-interest balances grow while you focus elsewhere
You may pay significantlymore interest over time
It can give a false sense of “winning” while expensive debt remains
Snowball isn’t bad — but it’s not free. You’re trading lower stress now for higher cost later.
Snowball vs Avalanche Comparison Table
| Feature | Debt Snowball | Debt Avalanche |
|---|---|---|
| Focus | Smallest balance first | Highest interest first |
| Psychological effect | Quick wins, motivation boost | Less visible progress early |
| Interest savings | Usually higher total interest | Lower total interest if consistent |
| Best for | People who need visible progress | People disciplined with cash flow |
| Time to payoff | Can be longer if interest is high | Typically shorter if consistent |
| Risk | Accumulates interest on large balances | Can demotivate if first balance is very large |
| Flexibility | Easy to switch or combine | Requires commitment, may need hybrid approach |
Why Calculators Don’t Match Real Outcomes
Debt calculators assume:
Interest rates stay the same
You never miss a payment
Minimum payments don’t increase
You never add new debt
In reality:
APRs change
Penalty rates can kick in
Minimum payments rise as balances shift
Emergencies happen
That’s why people often say, “The calculator said I’d be debt-free in 3 years… but it didn’t happen.”
The method didn’t fail. The assumptions did.
When Balance Transfers Make Things Worse, Not Better
Balance transfers sound smart — lower interest, faster payoff.
They can help, but only in narrow situations.
They often backfire when:
You don’t pay off the balance before the promo ends
You keep using the old card “just in case”
Transfer fees wipe out interest savings
Your credit score drops due to new inquiries or high utilization
Most people underestimate the risk of promo APRs ending because the deadline feels far away at first. By the time it’s close, the balance feels “normal,” and urgency quietly disappears.
A balance transfer is a temporary tool, not a solution. If spending habits or cash flow don’t change, the debt usually comes back — sometimes bigger.
Psychological Traps People Don’t Admit
These are rarely discussed, but they matter more than strategy:
Debt fatigue: After months of effort, people loosen up “just once”
False progress: Paying off a small card while ignoring a growing one
Perfection paralysis: Delaying action because you want the “best” method
Shame avoidance: Not checking balances because it feels heavy
If a method increases stress or guilt, it usually doesn’t last — no matter how logical it is.
A More Realistic Way to Choose Between Snowball and Avalanche
Instead of asking “Which method is best?”, ask:
Which debt creates the most stress when I see it?
Which payment, if removed, would free up cash fastest?
Can I realistically stay consistent for 6–12 months?
For some people, that’s avalanche.
For others, it’s snowball.
Many succeed by using a hybrid approach — knocking out one small balance, then switching to high-interest focus.
That flexibility matters more than purity.
What Success Actually Looks Like (No Hype)
Paying off credit card debt is rarely fast or dramatic. It usually looks like:
Fewer missed payments
Gradually lower stress
One balance gone, then another
Slower progress than you hoped — but steady
If you reduce chaos, avoid new debt, and stay consistent, you’re doing it right, even if the method isn’t perfect.
The goal isn’t to win a math contest.
It’s to get out of debt without burning out.
Before you decide anything, pause and reflect honestly on what stresses you most — slow progress, high interest, or juggling multiple balances. The right choice isn’t about perfect math; it’s about a path you can actually follow and maintain. Slow and steady still counts as progress.
FAQ Section Suggestions
A simple explanation: pay off your smallest debt first while making minimum payments on larger ones, then roll over payments to the next smallest.
Focus on the highest-interest debt first to minimize total interest, while paying minimums on the rest.
t depends on your situation: snowball helps with motivation, avalanche saves money. Many people use a hybrid of both.
Yes, adjusting your strategy as your financial situation or motivation changes is common.
Only if you can pay off the transferred balance before the promotional APR ends and you don’t add new debt.
Timelines vary depending on payments, interest rates, and method. Using calculators or simple projections helps estimate realistic timelines
Disclaimer:
The information provided in this article is for educational purposes only and should not be considered as financial advice. Always consult with a financial advisor or credit counselor before making any significant decisions regarding debt repayment or financial strategies. The strategies discussed may not be suitable for everyone and results may vary depending on individual circumstances.