

Starting a business is exciting — until you try to open a business credit card and get denied because your “business credit score” doesn’t exist yet.
Here’s the thing most people don’t tell you: every established business you admire started in the same spot. No credit history. No track record. And the banks? They don’t care about your business plan or your hustle. They want numbers.
That’s where a secured business credit card comes in.
It’s not glamorous. You’re essentially giving a bank your own money to borrow back from them. But for millions of small business owners in 2026, this is the smartest first move — the one that opens every door that comes after.
This guide breaks down exactly how these cards work, which ones are worth your deposit right now, and how real business owners are using them to go from zero credit to qualifying for real financing.
📌 If you’re an immigrant entrepreneur building business credit in the U.S. for the first time, also check out our guide on how to build your credit score as a beginner in the USA.
What Is a Secured Business Credit Card?
A secured business credit card is a credit card that requires you to put down a cash deposit upfront — and that deposit becomes your credit limit.
Put down $2,000, and you get a $2,000 credit line. The deposit acts as collateral for the card issuer, protecting them if you can’t pay back what you spend. Brex
From there, it works exactly like a regular credit card. You make purchases, pay your bill each month, and your payment history gets reported to business credit bureaus. Do that consistently for 12–18 months, and you’ll likely qualify for a real unsecured card — at which point the bank returns your deposit.
Think of it as paying admission to get into a game that everyone else already started without you.
Why Does Business Credit Even Matter?
Your personal FICO score (the 300–850 number) and your business credit score are completely separate things. Business credit scores are measured on a range from 1 to 100 by bureaus like Dun & Bradstreet and Experian. Slash
Why does this matter? Because when your business eventually needs a loan, a lease, better vendor terms, or a higher-limit card, lenders will pull your business credit — not just your personal score. By proving your business can use credit responsibly, you gain access to other forms of credit over time. Bill.com
Starting that business credit file now — even with a secured card — is one of the best financial moves any new business owner can make.

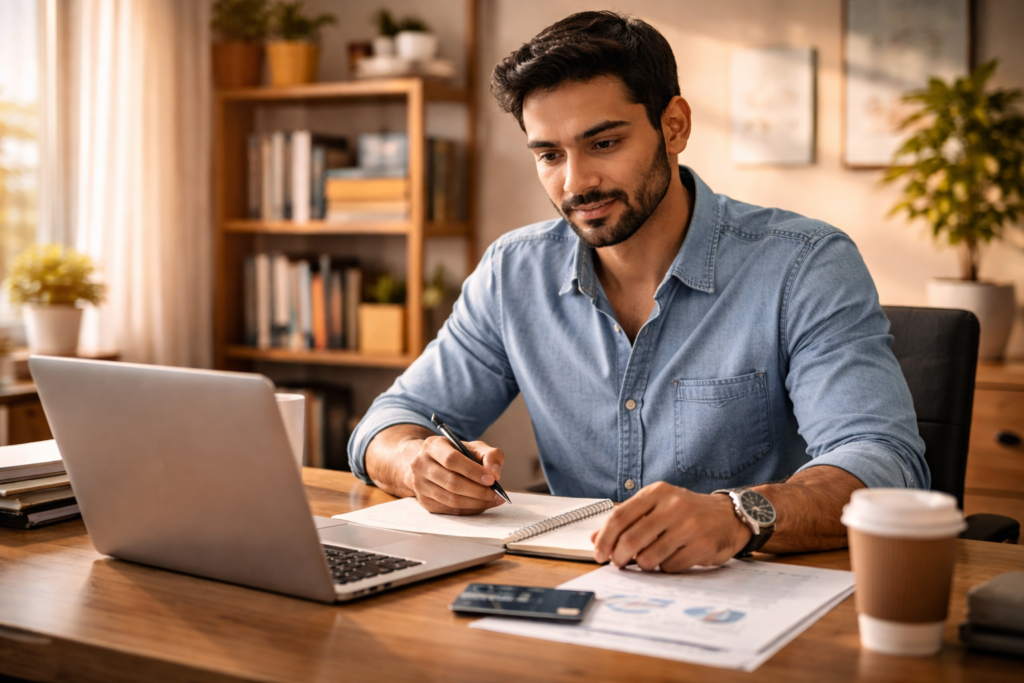
Secured vs. Unsecured Business Credit Card: The Real Difference
| 🔒 Secured Card | ✓ Unsecured Card | |
|---|---|---|
| Deposit required? | Yes — typically equals credit limit | No |
| Credit score needed | Low or none | Usually 670+ personal FICO |
| Credit limit | Equal to your deposit | Based on income / creditworthiness |
| Reports to bureaus? | Usually business bureaus | Yes |
| Path to upgrade? | Yes, after 12–18 months | Already unsecured |
| Annual fee | $0–$35 range | Varies widely |
💡 Tip: Secured cards are ideal for building or rebuilding business credit from scratch.
After demonstrating responsible use through 12 to 18 months of on-time payments, many issuers will return your security deposit and transition you to an unsecured card. Brex
The honest trade-off: you’re tying up cash you could use elsewhere. For a business with tight working capital, a $1,000 deposit sitting at a bank doing nothing is a real cost. But if the alternative is operating with zero credit history — and therefore no access to business financing of any kind — the deposit is worth every penny.
Who Actually Needs a Secured Business Credit Card?
Here are the business owners for whom this card makes clear sense:
1. New business owners with no business credit history Your business has never had a credit card, line of credit, or loan in its name. Most lenders will reject a standard application on those grounds alone.
2. Business owners with personal credit below 670 Most business credit cards require a personal credit score of at least 690. Secured options extend that benefit to those with lower scores. NerdWallet
3. Immigrants and recent arrivals to the U.S. Many immigrants have excellent financial habits but thin U.S. credit files. A secured card starts building both personal and business credit simultaneously.
If you’re an H-1B visa holder or recent immigrant navigating U.S. finances from scratch, our guide on building credit in the USA as a beginner and our piece on H-1B credit card options are worth reading alongside this one.
4. Business owners rebuilding after financial setbacks If your business — or personal — credit took a hit from a rough period, a secured card is the structured path back.
5. Solopreneurs and freelancers formalizing their businesses You’ve been running income through your personal accounts for years. A secured business card separates those expenses and starts building a legitimate credit profile for your business.

Best Secured Business Credit Cards in 2026
Honestly, the secured business card market is small. There just aren’t that many options. But the ones that exist are genuinely useful — and picking the right one matters because your deposit will be sitting there for a year or more.
Here’s a breakdown of every card worth considering right now.
Bank of America Business Advantage Unlimited Cash Rewards Secured Card
Only secured business card from a major national bank — and it's genuinely good. Not "good for a secured card." Good, period.
| 💳 Annual Fee | $0 |
| 💰 Minimum Deposit | $1,000 |
| 🎁 Cash Back | Unlimited 1.5% on all purchases |
| 🚫 Rewards Cap | None |
| ✈️ Foreign Transaction Fee | 3% |
| 📈 Upgrade Path | Yes — BofA reviews for unsecured upgrade |
| 📊 D&B Score Access | Yes, included in online banking |
Bank of America is the only major credit card issuer with a secured option for business owners. This card’s 1.5% cash back is the highest available among secured business cards. Many secured cards offered no rewards, yet still charged annual fees. Bank of America’s card has neither. NerdWallet
The $1,000 minimum deposit is the main hurdle. That’s real money for a lean startup. But the upside is that you get a $1,000 credit line, earning rewards on purchases while actively building both your business credit and your relationship with a major bank — a relationship that could lead to much better products down the road.
Bank of America will automatically review the cardholder’s credit history, and customers who pay on time and meet other qualifications may be able to transition to an unsecured card. Bank of America business credit cards generally report to SBFE (Small Business Financial Exchange). Nav
Best for: Small business owners who can put up $1,000 and want the best-rewarded secured card available.
Watch out for: High APR if you carry a balance, and the 3% foreign transaction fee if you buy internationally.
Valley Bank Visa Secured Business Credit Card
| 💳 Annual Fee | $0 |
| 💰 Minimum Deposit | $300 (110% of desired credit limit) |
| 📈 Max Credit Limit | Up to $25,000 |
| 🎉 Intro APR | 0% for first 6 billing cycles |
| 📊 Ongoing APR | 14.95%–26.25% variable |
| 🎁 Cash Back | 1% on all purchases |
| 📍 Availability |
Alabama
California
Florida
New Jersey
New York
In-person application only
|
The Valley Visa Secured Business Credit Card works for businesses looking to make a big purchase soon, as it comes with a 0% intro APR on purchases for the first 6 billing cycles, then 14.45% to 25.75% variable. FinanceBuzz
The 0% intro APR is a rare find on a secured card. If you’re planning a one-time larger business purchase and want to spread the cost over a few months, this card gives you a window to do that without interest — even though you’ve put up collateral.
The in-person application requirement is a real limitation, though. You have to walk into a Valley Bank branch. Not available online. Not available in most states. If you’re outside those five states, this one’s off the table.
Best for: Business owners in NJ, FL, AL, CA, or NY who need a higher credit limit and want a 0% intro period.
FNBO Business Edition Secured Mastercard
| 💳 Annual Fee | $39 |
| 💰 Minimum Deposit | $2,000 |
| 📈 Max Credit Limit | Up to $100,000 |
| 📊 APR | Variable |
| ✨ Unique Feature | You can request your own credit limit |
The First National Bank of Omaha Business Edition Secured Mastercard offers the unique luxury of allowing you to request your own credit limit — from $2,000 all the way up to $100,000. FinanceBuzz
Most secured cards are capped at $5,000–$25,000. If you’re a more established business that just has a thin credit profile (not bad credit, just no credit), and you can put up a larger deposit, FNBO gives you far more spending power than anything else in this category.
The $39 annual fee is the only real downside. With the Bank of America card available at $0, you’re paying $39 purely for the flexibility of a higher deposit tier. That may or may not be worth it depending on your situation.
Best for: Established businesses that need higher spending limits and can afford a larger security deposit.
Capital One Quicksilver Secured Cash Rewards Card
| 💳 Annual Fee | $0 |
| 💰 Minimum Deposit | $200 |
| 📈 Max Credit Limit | $3,000 |
| 📊 APR | 29.99% variable |
| 🎁 Cash Back |
1.5% on all purchases
5% on Capital One Travel hotels & rentals
|
| 🔍 Credit Check? | Yes |
| 📝 Note | Personal card — does not report to business bureaus |
With a security deposit minimum of only $200 and no annual fee, the Capital One Quicksilver Secured Cash Rewards Credit Card is a good choice for small business owners seeking easy entry. While it does come with a relatively high APR of 29.99%, this card offers automatic credit monitoring tools and 1.5% cash back on every purchase. A maximum credit limit of $3,000 means it isn’t meant for scaling businesses, but will work well with solopreneurs and small startups. Slash
The important caveat: this is technically a personal card. If you use it for business expenses, it builds your personal credit, not your business credit. That’s still useful — your personal credit score affects business loan approvals — but it won’t build a business credit profile at Dun & Bradstreet or Experian Business.
For someone who absolutely cannot afford the $1,000 deposit the Bank of America card requires, this is a reasonable starting point.
Best for: Solopreneurs and freelancers who want the lowest entry point and are building personal credit simultaneously.
OpenSky Secured Visa Credit Card
| 💳 Annual Fee | $35 |
| 💰 Minimum Deposit | $200 |
| 🔍 Credit Check? | None required |
| ✅ Approval Rate | Very high |
| 📊 Reports To |
All 3 personal credit bureaus
Not business bureaus
|
| 📈 Auto Credit Increase | Yes — after 6 months |
If you’ve had serious credit issues — bankruptcies, charge-offs, judgments — and you’re worried about getting rejected even for a secured card, OpenSky is likely your best shot. No credit check at all.
Small business owners who can only afford smaller deposit amounts (between $200 and $3,000) may start building credit fairly quickly with this card. The personal secured credit card comes with a $35 annual fee, but since there are no rewards to offset this fee, you’ll need to be okay with paying it to potentially build credit. Since it’s a personal card, your payment history won’t be reported to the business credit bureaus. FinanceBuzz
Like the Capital One option, this is a personal card — so it builds personal, not business, credit. But sometimes, getting your personal credit score up first is the fastest path to eventually qualifying for a business card.
Best for: Business owners with severely damaged credit who need a starting point with zero chance of rejection.
Nav Prime Card
| 💳 Annual Fee | $0 first year Then $25/year |
| 📊 APR | 27.49% variable |
| ✨ Unique Feature | Tradeline reporting to business bureaus — even without spending |
| 🔍 Hard Credit Check? | No |
Most cards only build credit when you spend. Nav Prime reports a tradeline to business bureaus automatically — making it one of the fastest ways to establish a business credit profile from scratch, even if you never swipe the card.
Nav Prime is different from the other options. It’s not a credit card in the traditional sense — it’s a credit-building tool that reports to business credit bureaus as a tradeline. This means even if you just have the card and make minimum payments, it’s actively building your business credit file.
For immigrants and new business owners who want to establish a business credit profile as quickly as possible without tying up a large deposit, this is worth a look alongside a traditional secured card.

Real Stories: What Small Business Owners Are Saying
These are real experiences shared publicly in small business and finance communities — the kind of honest feedback you won’t find on a bank’s website.
From r/smallbusiness (Reddit):
One business owner described opening the Bank of America secured card after getting rejected twice for regular business cards:
“Put down $2,000 as the deposit. Felt weird handing over that money. Used it for all my recurring software subscriptions — kept the balance under $400 so my utilization stayed low. Thirteen months later, Bank of America called and offered to convert it to an unsecured card and return my deposit. That’s when I knew I’d done it right.”
From r/startups (Reddit):
A first-time founder shared frustration — and a lesson — after picking the wrong card:
“I went with a card from a credit union that didn’t report to Dun & Bradstreet. Paid every month, perfect record. A year later, my D&B score was still basically blank. Total waste. Always check which bureaus the card reports to before applying.”
This is one of the most common mistakes new business owners make. Always confirm the card reports to SBFE, Dun & Bradstreet, Experian Business, or Equifax Business — not just to personal bureaus.
From a Facebook small business group (Indian Entrepreneurs in the USA):
“As an H-1B holder trying to start a side LLC, nobody told me my personal credit score and my business credit were completely separate things. I had a 780 personal score but literally zero business credit. Started with the BoA secured card, added a few net-30 vendor accounts, and within 8 months my Paydex score (D&B) was above 80. Now applying for a real business line of credit.”
This story highlights something important for immigrants building businesses in the U.S.: having great personal credit doesn’t automatically help your business. You need to build the business credit file separately — and a secured card is usually the first step.
📌 Read more about this in our guide on how H-1B visa holders can build credit in the USA.
How to Apply for a Secured Business Credit Card: Step-by-Step
Applying is straightforward, but there are a few things to get right.
Step 1: Have Your Business Information Ready
Even if your business is brand new, you’ll need:
- Business name (or your own name if sole proprietor)
- EIN (Employer Identification Number) — or Social Security number for sole proprietors
- Business address and phone number
- Annual revenue estimate (you can enter $0 if you’re just starting)
- Industry type
📌 Don’t have an EIN yet? You can get one free from the IRS at IRS.gov in about 10 minutes online. It’s important for separating your business finances — see also our guide on EIN-only business credit cards.
Step 2: Check Your Personal Credit Score First
A personal credit check is part of the credit card application process for most secured business cards, even though they’re more flexible than traditional cards. Nav Knowing where you stand helps you pick the right card and avoid hard inquiries from cards you won’t qualify for.
📌 See our full breakdown on how credit scores work in the USA to understand exactly what lenders see.
Step 3 — Pick the right card for your situation
| Your Situation | Best Card |
|---|---|
| 💰 Can put down $1,000, want best rewards | 🏦 Bank of America Secured |
| 📍 In NJ / FL / AL / CA / NY, need high limit | 🏛️ Valley Bank Visa Secured |
| 📈 Need $50K+ credit limit | 🏢 FNBO Business Edition Secured |
| 💵 Can only put down $200 | 💳 Capital One Quicksilver Secured |
| 🚫 Very bad credit, need no credit check | 🌤️ OpenSky Secured Visa |
| 🧭 Want to build business credit without large deposit | 🧭 Nav Prime |
Step 4: Submit the Application
For most cards, this is online. Valley Bank requires an in-person application. Have your deposit ready — it’s typically debited shortly after approval.
Step 5: Fund the Security Deposit
Your deposit is typically transferred electronically from your bank account within a few business days of approval. Once funded, your card arrives within 7–10 business days.
Step 6: Use It Strategically
This part matters more than the application.
- Keep utilization below 20–30% of your credit limit. High utilization hurts your score even on a secured card.
- Pay in full every month — carrying a balance at 20%+ APR is expensive and unnecessary.
- Use it for recurring, predictable expenses — software subscriptions, phone bills, office supplies — so you never forget a payment.
- Set up autopay from day one.
How to Graduate From a Secured to an Unsecured Card
After 12 to 18 months of on-time payments, many issuers will return your security deposit and transition you to an unsecured card. Brex
Here’s how to accelerate that process:
1. Never miss a payment. One late payment can reset the clock. Autopay for at least the minimum — pay the full balance manually if you prefer.
2. Keep utilization low consistently. Aim to report a balance of 10–20% of your credit limit at each statement date, not 80%.
3. Add vendor tradelines. Apply for net-30 accounts with vendors like Uline, Grainger, or Quill. These report to business credit bureaus and build your file faster. Read our full guide on best tradelines to build business credit.
4. Open a dedicated business bank account. Having business checking and your secured card at the same bank (especially Bank of America) can speed up their internal review for upgrading your card.
📌 Don’t have a U.S. business bank account yet? See our guide on how to open a bank account in the USA.
5. Ask. After 12 months, call or message the bank and ask directly about converting to an unsecured product. Some banks do automatic reviews; others need you to initiate.
Common Mistakes to Avoid
Mistake 1: Picking a card that doesn’t report to business credit bureaus. This is the most costly mistake. Spend 12 months being responsible, and if the card only reports to personal bureaus, your business credit file is still empty. Always verify — call the issuer if you can’t find this information online.
Mistake 2: High credit utilization. Running your secured card close to the limit every month signals risk to credit bureaus, even if you pay it off. Keep the reported balance low.
Mistake 3: Using it as a cash flow tool. These cards have high APRs — often 20–29%. Carrying a balance is expensive. Use a secured card to build credit, not to borrow money.
Mistake 4: Applying for too many cards at once. Each application triggers a hard inquiry on your personal credit report. Multiple hard inquiries in a short window hurt your score. Pick one card and commit.
Mistake 5: Forgetting the deposit is real money. If your business closes or you default, you can lose the deposit. It’s not free insurance — it’s collateral. Keep that in mind when deciding how much to deposit.
📌 Also see our guide on the best strategies to pay off credit card debt — useful context if you’re managing multiple cards.

Frequently Asked Questions
Yes. Secured cards exist specifically to reduce issuer risk while enabling early-stage founders to establish a credit history from scratch. Slash The deposit is your guarantee to the bank, so traditional credit score requirements are much lower or nonexistent.
It depends on the card. Most secured business cards run a hard inquiry on your personal credit when you apply, which may lower your personal score by a few points temporarily. However, ongoing payment activity on a true business card typically doesn’t appear on your personal credit report — unless you default.
Deposit what you can afford to have locked up for 12–18 months. More deposit = more credit limit = more flexibility for business expenses. But don’t deposit money your business needs for operations. A common approach: deposit 2–3 months’ worth of your regular business expenses so you can actually use the card without maxing it out.
Some corporate cards (Brex, Ramp) don’t require a personal guarantee, but they require established revenue and bank balances that most new businesses don’t have. For true beginners, most secured cards will ask for your SSN and run a personal credit check. Learn more in our detailed guide on EIN-only business credit cards.
Three-pronged approach: (1) Get a secured business card that reports to business bureaus, (2) add net-30 vendor tradelines, (3) make sure your business is registered with Dun & Bradstreet. With all three running simultaneously, many business owners see a meaningful Paydex score within 6–9 months. Read our full guide on the best tradelines to build business credit.
After 12 to 18 months of consistent on-time payments, many issuers will return your security deposit and transition you to an unsecured card. Brex Some banks do this automatically; others require you to apply for an upgrade. Bank of America, for example, reviews accounts periodically and may proactively offer the upgrade.
If your personal credit is strong (700+), you may qualify for a real unsecured business credit card — no deposit needed. Check those options first. You’d only want a secured business card if you specifically can’t qualify for any unsecured option, or if you want a strategic tool to establish a business credit file independent of your personal credit. See our guide on how credit scores work in the USA to understand where you stand.
The 2026 Landscape: What’s Changed
A few notable shifts in 2026 worth knowing:
- Hello Alice Small Business Secured Mastercard shut down in March 2025. This was a popular recommendation for a while. It’s no longer available. Any article still recommending it is outdated — verify before applying anywhere.
- NerdWallet added a small deduction in 2026 for secured business cards that don’t allow users to issue virtual cards — reflecting how important digital financial tools have become even for small businesses. NerdWallet
- The secured business card market remains thin. There simply aren’t many options compared to the unsecured market. The Bank of America card continues to dominate recommendations across every major financial publication.
- Corporate cards like Brex and Ramp have improved, but they remain inaccessible to true startups without revenue. They’re not real alternatives for the audience that needs secured cards.
Bottom Line: Which Card Should You Get?
If you can put down $1,000 and you’re in most U.S. states: Bank of America Business Advantage Unlimited Cash Rewards Secured is the clear winner. No annual fee, 1.5% cash back, reports to business bureaus, and a legitimate path to a major bank unsecured card.
If you’re in NJ, FL, AL, CA, or NY and want higher limits: Valley Bank Visa Secured is worth the in-person application.
If your personal credit is severely damaged and you just need to get started: OpenSky Secured Visa has no credit check.
If $1,000 is too much to lock up right now: Capital One Quicksilver Secured gets you in the game for $200 — just remember it builds personal, not business, credit.
Whatever you choose, treat the secured card like training wheels, not a destination. Your goal from day one is to use it responsibly and graduate to real business financing. That process takes time, but it’s completely predictable: pay on time, keep utilization low, add a few tradelines, and the doors open.
Disclaimer
Financial Advice Disclaimer: The information provided in this article, “Best Secured Business Credit Cards in 2026,” is for informational and educational purposes only. It does not constitute professional financial, legal, or tax advice. While we strive to provide accurate and up-to-date information, credit card terms, interest rates, and bank policies change frequently.
No Guarantee of Approval: Applying for a credit card involves a risk to your credit score, and approval is never guaranteed. We are not responsible for any financial decisions made based on this content. We strongly recommend consulting with a certified financial advisor or a tax professional before making significant financial commitments.
Affiliate Disclosure (Optional – Agar aap links se paise kamate hain): Some of the links in this article may be affiliate links. This means that at no additional cost to you, we may receive a small commission if you click through and get approved for a card. This helps us keep our content free and high-quality.