usaharmony.comusaharmony.comusaharmony.com
  • Finance
    • Banking in USA
    • Budgeting & Saving
    • Credit Score USA
  • U.S. Immigration Guide
Reading: How to Start Investing With Little Money in 2026:A Beginner’s Guide (U.S.)
Share
Sign In
Notification
Font ResizerAa
usaharmony.comusaharmony.com
Font ResizerAa
  • Finance
  • U.S. Immigration Guide
Search
  • Finance
    • Banking in USA
    • Budgeting & Saving
    • Credit Score USA
  • U.S. Immigration Guide
Have an existing account? Sign In
Follow US
Copyright © 2026 USAHARMONY

Home » Budgeting & Saving

Budgeting & Saving

How to Start Investing With Little Money in 2026:A Beginner’s Guide (U.S.)

Jacob Charles
Last updated: 26 February 2026 07:39
Jacob Charles
Share
7 Min Read
how to start investing with little money
You don’t need a lot of money to begin investing—you need clarity and consistency.
SHARE

A Beginner’s Guide Written by a U.S. Finance Expert

Many people believe investing is only for those who already have a lot of money. In my experience working with first-time investors across the United States, that belief stops more people from building wealth than any market crash ever has.

Contents
A Beginner’s Guide Written by a U.S. Finance ExpertWhy Starting With Little Money Still MattersWhat “Little Money” Really Means (Let’s Be Honest)Common Myths That Stop Beginners From InvestingStep-by-Step: How to Start Investing With Little MoneyReal Beginner Scenarios (What Actually Works)Pros and Cons of Starting With Little MoneyComparing Beginner Investment Options30 / 90 / 365 Day Beginner TimelineCommon Beginner Mistakes (That Top Articles Don’t Warn You About)What NOT to Do When You Start InvestingFrequently Asked QuestionsTrusted U.S. ResourcesFinal ThoughtsDisclaimer:

The truth is simple: you do not need a large amount of money to start investing. What you need is clarity, realistic expectations, and a system that works with small amounts—not against them.

This guide explains how to start investing with little money, step by step, in plain language. No hype. No shortcuts. Just practical advice you can actually follow.

Why Starting With Little Money Still Matters

One of the biggest misconceptions beginners have is that small investments “don’t matter.” That’s wrong.

What matters most in investing is time, not the starting amount.

Real-life example

I once helped a 24-year-old retail worker who started investing just $75 per month. It didn’t feel like much. But over time, consistency mattered more than the amount. Five years later, they had built discipline, confidence, and a solid base—something most people never achieve.

What “Little Money” Really Means (Let’s Be Honest)
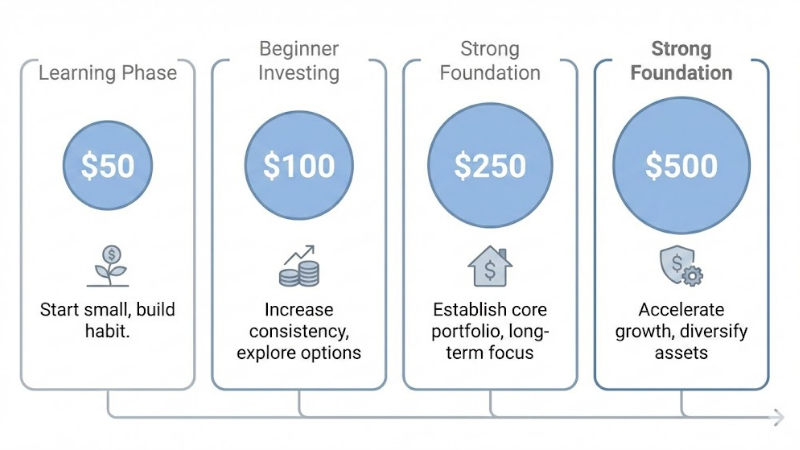
investing with little money examples
Even small monthly amounts can build strong investing habits over time.

Different articles avoid defining this clearly. Let’s fix that.

Monthly AmountWhat It Means in Practice
$25–$50Learning phase, habit building
$100Real investing begins
$250–$500Strong foundation potential
$1,000+Advanced beginner territory

If you are in the $50–$200 range, you are exactly where most successful investors started.

Common Myths That Stop Beginners From Investing


Myth 1: “I’ll start when I earn more”

Most people never start because income always finds a way to get used elsewhere.

Myth 2: “Investing is basically gambling”

Speculation is gambling. Long-term investing is ownership.

Myth 3: “I need to pick winning stocks”

You don’t. In fact, beginners should avoid stock picking early.

Step-by-Step: How to Start Investing With Little Money


Step 1: Make Sure You’re Ready (Before Investing)

Before investing a single dollar, check these boxes:

  • You can pay monthly bills

  • You have$500–$1,000 emergency cash

  • You are not using credit cards for essentials

If these aren’t in place, investing can backfire emotionally and financially.

Step 2: Set a Simple Goal (Not a Big One)

Beginners fail when goals are vague.

Good beginner goals:

  • “Invest $100 per month for one year”

  • “Build my first $1,000 invested”

  • “Learn how markets move without panic”

Bad goals:

  • “Get rich fast”“Beat the market”

Step 3: Understand Your Investment Account Options (U.S.)

This is where many articles get confusing. Let’s simplify.

Account TypeBest ForMinimum
Brokerage accountGeneral investing$0–$100
Roth IRALong-term retirement$0–$100
Robo-advisorHands-off beginners$50–$500

If you’re working and earning income, a Roth IRA is often the best long-term choice.

Step 4: Choose Beginner-Friendly Investments

Avoid complexity early.

Best options for small investors:

InvestmentWhy It Works
Index fundsBroad market exposure
ETFsLow cost, flexible
Robo-advisor portfoliosAutomatic diversification

What NOT to start with:

  • Day trading

  • Options

  • Penny stocks

  • Crypto speculation

These destroy beginner confidence.

Step 5: Automate Everything

In real situations, users often fail not because of bad investments—but because they stop contributing.

Automation removes emotion.

Set:

  • Monthly auto-deposit

  • Automatic investment allocation

Consistency beats intelligence here.

Real Beginner Scenarios (What Actually Works)

Scenario 1: College student with $50/month

  • Opens brokerage account

  • Buys total market ETF

  • Focus: learning, not returns

Scenario 2: Working adult with $200/month

  • Uses Roth IRA

  • Invests in index fund

  • Adds slowly with raises

Scenario 3: Side-hustler with irregular income

  • Keeps cash buffer

  • Invests only surplus

  • Avoids forced contributions

Pros and Cons of Starting With Little Money

Pros

  • Low emotional risk

  • Builds discipline

  • Teaches market behavior

  • Easier recovery from mistakes

Cons

  • Slower visible growth

  • Fees matter more

  • Requires patience

Both are normal. Growth comes later.

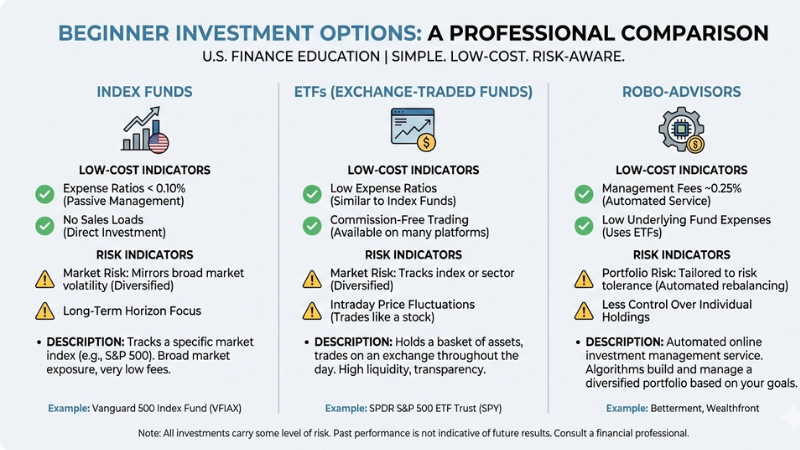
Comparing Beginner Investment Options

OptionRiskControlBest For
Index fundLow-MediumMediumLong-term growth
ETFLow-MediumHighFlexible investors
Robo-advisorLowLowHands-off beginners
Individual stocksHighHighLater stage only
beginner investment options comparison
Simple, diversified investment options work best for beginners.

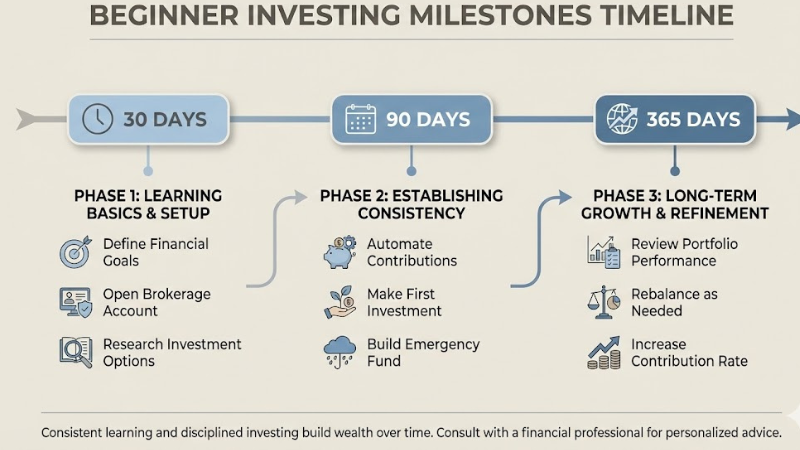
30 / 90 / 365 Day Beginner Timeline

investing timeline for beginners
Investing progress happens over months and years—not days.

First 30 Days

  • Learn terminology

  • Set up accounts

  • First investment made

First 90 Days

  • Market ups and downs experienced

  • Confidence tested

  • Automation proves useful

First Year

  • Habit solidified

  • Understanding improves

  • Returns become secondary to consistency

Common Beginner Mistakes (That Top Articles Don’t Warn You About)
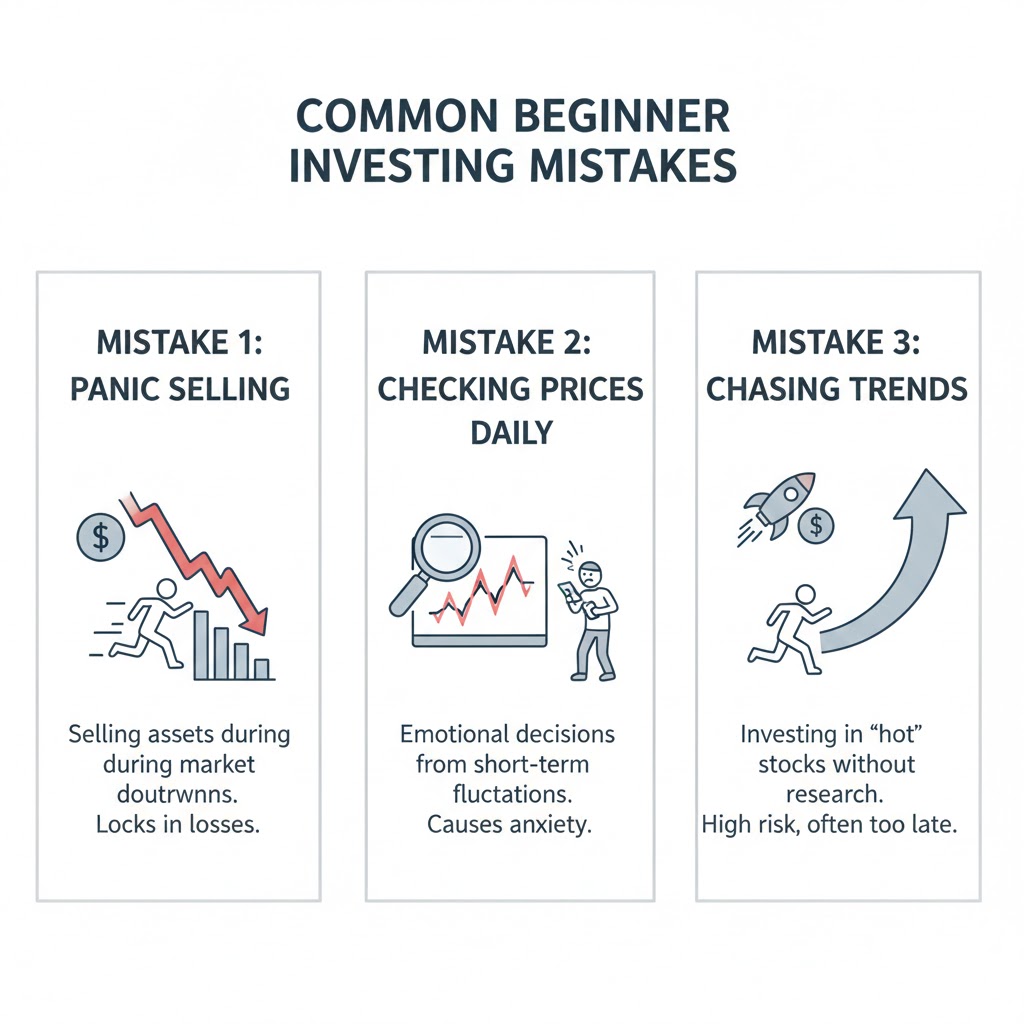
beginner investing mistakes
Avoiding common mistakes matters more than finding perfect investments.
  •  Watching daily market news
  • Panic selling during dips

  • Constantly switching strategies

  • Comparing yourself to others

  • Overestimating short-term returns

In my experience, staying boring is what works.

What NOT to Do When You Start Investing

  • Don’t invest emergency money

  • Don’t chase trends

  • Don’t copy influencers

  • Don’t ignore fees

  • Don’t expect quick results

Frequently Asked Questions

Can I really start investing with $50?

Yes. The goal is learning and consistency, not speed.

Is investing with little money worth it?

Yes—because habits compound before money does.

Should beginners invest in stocks?

Not individual stocks at first. Use funds.


How long before I see results?

Months for learning. Years for meaningful growth.

Is investing risky for beginners?

Risk exists, but proper diversification controls it.

Trusted U.S. Resources

  • https://www.investor.gov

  • https://www.myfico.com

  • https://www.consumerfinance.gov

Final Thoughts

Starting to invest with little money isn’t about returns—it’s about becoming an investor.

Once you build the habit, the confidence, and the system, increasing the amount becomes easy. Waiting for the “perfect time” never works. Starting small—but starting now—does.

In my experience, the people who succeed aren’t the ones who start big. They’re the ones who start anyway.

Disclaimer:

The content on USA Harmony is for informational and educational purposes only and should not be considered financial or investment advice. Financial situations vary, and readers should consult a qualified professional before making any investment decisions.
TAGGED:2026credit scorefinanceinvestingsaving
By signing up, you agree to our Terms of Use and acknowledge the data practices in our Privacy Policy. You may unsubscribe at any time.
Share This Article
Facebook Twitter Whatsapp Whatsapp LinkedIn Telegram Copy Link Print
Share
By Jacob Charles
Follow:
Jacob Charles is a U.S. personal finance and investment researcher with over five years of focused study on the American credit system, retirement account structures, and long-term wealth building strategies for individual investors. His expertise spans the full personal finance spectrum — from helping first-time credit card holders understand why their score dropped overnight, to walking experienced investors through the tax implications of a Roth IRA conversion, to explaining exactly what happens inside an S&P 500 index fund when markets fall 30 percent and why selling is almost always the wrong move. Jacob has spent years studying how everyday Americans — particularly those without a financial background — make decisions about money, where those decisions go wrong, and what the research actually says about the outcomes. That foundation drives every article he writes at USAHarmony. His research methodology is built entirely on primary sources. IRS tax code publications, CFPB consumer financial protection guidelines, Federal Reserve economic data, SEC investor education bulletins, FINRA regulatory notices, and official prospectus documents from major index fund providers form the core of every analysis he publishes. Secondary sources, opinion pieces, and unverified claims do not make it into his work — period. Jacob's particular focus is the gap between how personal finance is usually explained and how it actually works in practice. Most financial content either oversimplifies to the point of being misleading or buries the reader in technical language that assumes a finance degree. Jacob writes at neither extreme — his standard is that a reader with no financial background should be able to finish an article and make a real, informed decision based on what they just read. Topics he has covered in depth include credit score mechanics and the specific behaviors that move scores up and down, secured and unsecured credit card strategy for thin-file applicants, the Roth IRA income limits and contribution rules that most people get wrong, traditional versus Roth 401k tradeoffs at different income levels, S&P 500 index fund selection and the real cost of expense ratios over 30 years, debt payoff strategy using avalanche and snowball methods with actual mathematical comparisons, and the credit utilization patterns that most people misunderstand even after years of having a credit card. Every article published under Jacob's name at USAHarmony undergoes a structured review process before publication — claims are checked against current IRS and CFPB guidelines, figures are verified against the most recent official data releases, and articles are updated on a rolling basis whenever regulatory changes, new IRS contribution limits, or Federal Reserve policy shifts make earlier information outdated. Jacob holds the position that financial literacy is not a luxury — it is the difference between building wealth slowly and losing it quietly. His work is dedicated to making sure that difference is as clear as possible for every reader who lands on this site. Readers are always strongly encouraged to consult a licensed Certified Financial Planner, CPA, or registered investment advisor before making personal financial decisions. The content on USAHarmony is educational and informational in nature and does not constitute personalized financial advice.
Previous Article what causes your credit score to change What Causes Your Credit Score to Change? A Beginner’s Guide Explained Simply
Next Article "Smart $1000 split strategy: Building credit and investing simultaneously." How to Build Credit with $1000 Using a Secured Credit Card
Leave a comment Leave a comment

Leave a Reply Cancel reply

Your email address will not be published. Required fields are marked *

Stay Connected

TwitterFollow
- Advertisement -
Ad imageAd image

Latest News

Indian professional reviewing H-1B transfer documents at office desk in 2026
H-1B Transfer to New Employer in 2026: The Complete Step-by-Step Guide
Home 25 April 2026
H1B visa alternatives 2026 — professional exploring multiple US work visa options after lottery
H1B Visa Alternatives 2026: 10 Real Options After the Lottery
U.S. Immigration Guide 17 April 2026
Green card and H1B visa documents with financial planning notebook representing long-term immigration cost planning
H1B Visa Transfer Cost in 2026: What Employers and Workers Actually Pay
U.S. Immigration Guide 14 April 2026
H1B visa holder holding house keys outside newly purchased American home
H1B Visa Mortgage Loan 2026: Complete Guide to Buying a Home on a Work Visa
U.S. Immigration Guide 14 April 2026
usaharmony.comusaharmony.com
Follow US
Copyright © 2026 USAHARMONY
  • About – USAHARMONY
  • Terms and Conditions
  • Financial Disclosure & Editorial Disclaimer
  • Privacy Policy
  • Contact
Go to mobile version
usaharmony.com
Welcome Back!

Sign in to your account

Lost your password?